More from this author: Training Your Successor
Dealing With Workplace Fraud in Fleets
Workplace fraud in government organizations can result in significant financial losses, but understanding its causes and implementing effective controls can help mitigate the risk.
by Jeff Tews
August 10, 2026
Workplace fraud in government organizations can result in significant financial losses, but understanding its causes and implementing effective controls can help mitigate the risk.
Government Fleet
6 min to read
You don’t need to look hard to find examples of workplace fraud being reported each month. From employees charging personal expenses on their company-issued credit cards, theft of resources, misreporting hours worked and asset embezzlement, these and other examples of fraud are increasingly being discovered.
The US Department of Commerce estimates employee fraud costs businesses almost $50 billion a year. Some of the top workplace fraud statistics in private and public sector businesses indicate the following:
- 57% of frauds are committed by employees inside the organization or in combination with insiders and outsiders.
- 43% of employees exaggerate the work hours they report.
- 20% of data breaches are linked to inside employees.
- Embezzlement incidents lead to an average of $357,000 in loss per occurrence.
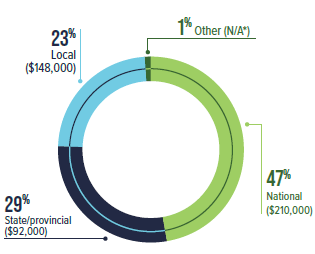
Effects of occupational fraud on government. Median losses are shown.
Photo: Association of Certified Fraud Examiners - 2024 Report to the Nations
Government agencies are also affected by employee fraud. About 17% of all investigations reveal fraud occurring within local, state and federal governmental institutions resulting in a median loss of $150,000 per incident.
The more prevalent forms of employee fraud investigated within governmental operations include corruption, asset misappropriation, fraudulent billing and expense reimbursements, cash and non-cash larceny, check and payment tampering, payroll schemes and skimming.
Who commits fraud within government organizations? According to Association of Certified Fraud Examiners (ACFE), 2024 Report to the Nations:
- Upper management represents 19% of cases resulting in $313,000 median loss over 24 months.
- Managers represent 39% of cases resulting in $224,000 median loss over 18 months.
- Employees represent 39% of cases resulting in $50,000 median loss over 12 months.
The above figures point to a curious trend. Instances of employee fraud are much more frequent than upper management frauds, but are detected much sooner and usually result in significantly lower median losses. Conversely, upper management frauds are usually carried out by trusted people in higher level positions, capable of covering their tracks for longer time periods before detection.
Who is Likely to Commit Fraud?
The typical fraud offender may look like any other employee, hardworking and trustworthy. Most fraudsters have no prior instances of workplace fraud, 55% have no history of misconduct and only 13% have a poor performance evaluation on record. Individual circumstances tend to lead employees to commit fraud more so than personality traits.
The National Association of State Auditors, Comptrollers and Treasurers (NASACT) created an estimate called the 10-80-10 Rule that claims most people can be incentivized to commit fraud under the right circumstances. Under the 10-80-10 Rule, it is assumed that:
- 10% of the people would never commit fraud, no matter the circumstances.
- 80% of people may commit fraud, given their individual circumstances.
- 10% of the people are actively looking for opportunities to commit fraud.
More than 50% of frauds are committed by employees inside the organization or in combination with insiders and outsiders, according to the US Department of Commerce.
Photo: Embroker.com
Understanding what leads workers to commit fraud can help managers work to prevent it, or at least detect it sooner and stop the fraud before massive losses result. One of the tools used is the Fraud Triangle, which was developed in the 1970s by criminologist Donald Cressey.
In this model, each point of the triangle represents three components that usually lead to higher instances of occupational fraud; motivation, opportunity and rationalization.
Motivation: Also known as “pressure”, the motivation to commit fraud may stem from sudden overwhelming expenses such as medical bills for a spouse or child, an addiction, the loss of a partner’s income, frustration with current job status, being passed over for a promotion, or even the pressure of trying to keep up with the successes of friends and family.
Opportunity: Most often, opportunities for fraud can occur when there is a lack of oversight or internal controls. These controls may be absent or non-existent, not enforced, ineffective, or unmonitored. Sometimes the perpetrator of fraud may work in conjunction with others in critical positions to override existing controls.
Rationalization: As the reasoning used to justify fraudulent acts, rationalization involves fabricating moral excuses that reconcile the instance(s) of committing fraud. This process is internal to the perpetrator. Many fraudsters view themselves as honest, hardworking ordinary people, not criminals. Common excuses used to rationalize fraud include beliefs such as:
- Everyone is doing it. It’s expected!
- The boss is earning so much more than what I make!
- We waste so much money anyway.
- It’s a loan. I’ll pay it back.
- Our operation is big enough that no one will notice.
- I deserve it after all these thankless years working here with no raises!
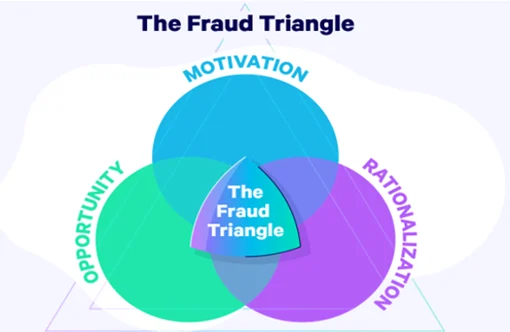
The easiest component of the Fraud Triangle to control is opportunity.
Graphic: Embroker.com
What Can You Do to Minimize Fraud?
Watch for the warning signs. According to ACFE, there are eight notable behavioral red flags to look out for. Of the following, 84% of fraudsters displayed at least one of these signs:
- Living beyond their means.
- Financial difficulties.
- Unusually close association with customers or vendors.
- Control issues, unwillingness to share duties.
- Irritability, suspiciousness, or defensiveness.
- “Wheeler-Dealer” attitude.
- Bullying or intimidation efforts.
- Divorce or family problems.
How well do you know your employees and peers? As a manager, you hopefully are close enough to understand potential motivations to commit fraud among your employees. Spending time with employees may allow you to notice sudden or gradual changes in behavior that could be signaling personal hardship or family tragedy.
This could give you the opportunity to offer some type of support. While it is true that managers in government usually cannot provide monetary relief, there are forms of assistance you can offer such as flexible hours, a different shift, donation of vacation time, or referral to an employee assistance agency that can help. Demonstrating empathy in good times and bad may give employees fewer reasons to turn to fraud.
The easiest component of the Fraud Triangle to control is opportunity. What anti-fraud controls do you have in place? Lack of internal controls, or overriding of existing controls contributed to over 50% of frauds reported.
The presence of robust anti-fraud controls is associated with lower fraud losses and quicker detection. The most common anti-fraud controls include:
- Codes of conduct.
- Anti-Fraud policies and training for both employees and managers.
- Routine and surprise audits of financial statements, internal and external.
- Anonymous hotline or tipline. (43% of fraud schemes were detected by a tip)
- Management reviews.
- Employee assistance programs.
- Real consequences for fraud policy violators that discourage new frauds.
Rationalization is the most difficult component to detect, since it takes place within the mind of the perpetrator based on their own set of morals. Even when employees have motivation and opportunity, most will choose not to act unless they can justify to themselves why their fraud is “Okay."
In addition to promoting employee fairness and having strong controls in place, reducing rationalization to commit fraud may be further accomplished if you champion transparency of organizational goals, operations and finances.
When employees understand that their own financial interests are tied to healthy business practices, they are more likely to engage emotionally in the success of the whole organization.
The convergence of motivation, opportunity and rationalization can form a perfect storm for costly employee misconduct. As pressure to commit fraud increases, a person who perceives an opportunity may look for ways to circumvent existing controls and may begin to rationalize these behaviors. On the other hand, fairly-compensated and content employees who feel valued and treated well may be far less inclined to commit fraud.
Take the time to review, analyze, modify and reinforce the controls you have in place. It should be noted that 82% of organizations modified their anti-fraud controls following damages caused by fraud, with 95% of those modifications expected to be effective at preventing future incidents of fraud.
Active enforcement and periodic reviews of internal controls and promoting a genuine team atmosphere work in conjunction with the constant vigilance required to reduce instances of workplace fraud.
Editor's Note: This article was originally publish in January 2026 and has been updated to meet Government Fleet's guidelines.
Subscribe to Our Newsletter
More Operations
Is Keeping Older Fleet Vehicles Really Saving Money?
Is keeping vehicles longer saving money, and what happens when a diagnostic test points to the wrong fix?
Read More →
How Smart Fleet Strategy Can Help Local Government Agencies Do More with Less
Keeping a vehicle longer may ease this year’s budget, but what does it cost the next one? A closer look at fleet decisions can reveal opportunities to reduce spending while protecting essential services.
Read More →
Connect with Government Fleet on LinkedIn
From industry news and fleet management strategies to conversations with peers, Government Fleet's LinkedIn page offers public-sector fleet professionals another way to stay informed and connected.
Read More →
Town of Queen Creek Named Most Successful Fleet Award Winner of Inaugural RTA Fleet Success Awards
Five fleets were honored at RTA Connect 2026 in Chicago for excellence across resource efficiency, intentional culture, risk management, and stakeholder satisfaction.
Read More →
Sponsored•October 14, 2026
A buyer's guide to fleet management software in 2027
Buying fleet management software in 2027 means looking beyond features and price. As fleet operations, technology and expectations evolve, this guide explores what today’s fleet professionals should consider when choosing a system that can deliver value now and adapt to what comes next.
Read More →
Hazard Alerts, Fleet Car Sales Rise and a New Shuttle Concept
Fleet car sales doubled, but the bigger picture tells a different story in this week’s roundup.
Read More →
How St. Johns County Turned Fleet Data Into Better Replacement Decisions
St. Johns County, Florida, had fleet data, but turning it into reliable decision guidance was another matter. Instead of starting over with a new fleet management system, the county connected existing tools and built a scoring system that gives managers an objective look at fleet health.
Read More →
Fleet Forward Conference Introduces One-Day Passes for 2026
New one-day registration lets fleet professionals attend Tuesday, Wednesday, or Thursday, with passes available for $249.
Read More →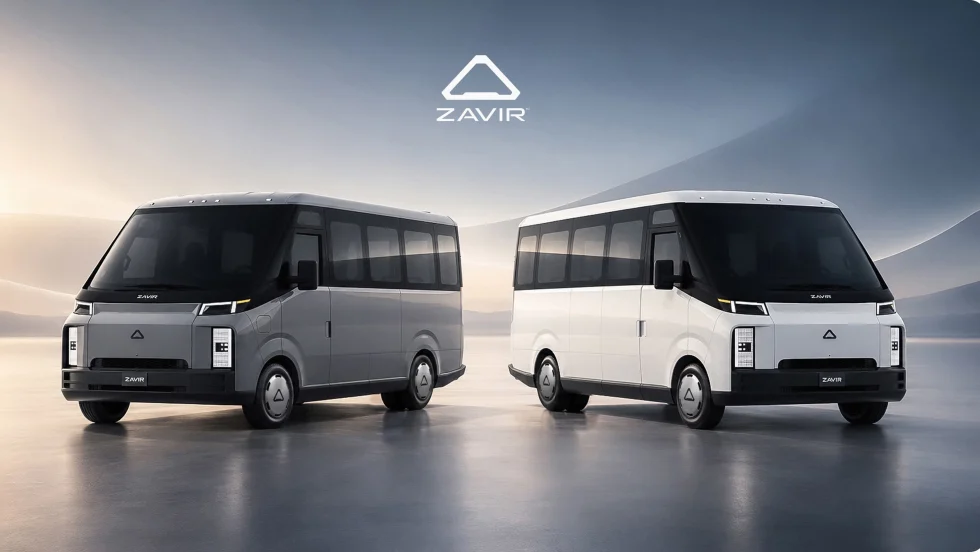
ENC Unveils its ZAVIR Medium-Duty Shuttle
Two variants of the concept shuttles were revealed: a low-floor configuration and a high-floor configuration.
Read More →
Could Your Next Fleet Technician Start as an Intern?
What if your next technician hasn’t worked in a fleet shop yet? What fleets are doing to free up time.
Read More →